Halfway Through 2026: The Nigerian Economy Report Card
Seven months since 'The Code and the Ledger' opened this journal with a call for a new kind of builder. Banks recapitalized, taxes got rebuilt, and a credit economy arrived faster than expected. Here is the scorecard on everything we called.
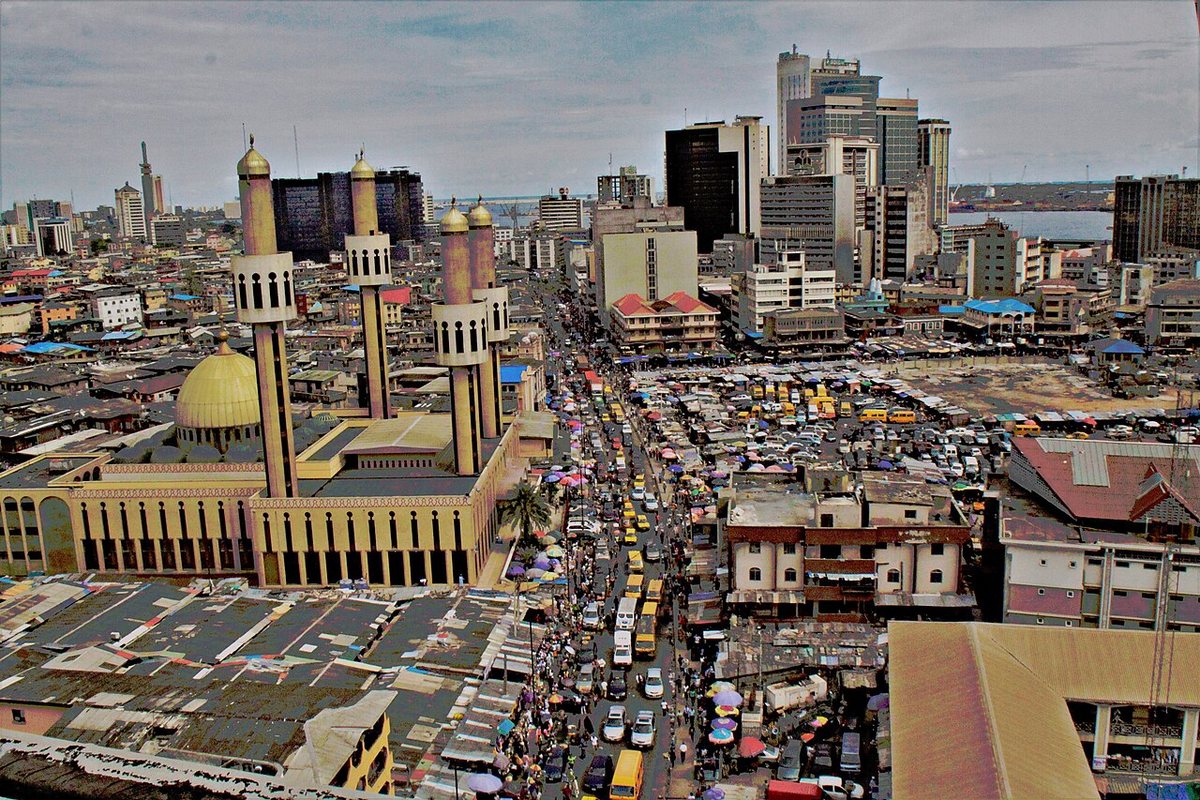
In January, this journal opened with a manifesto: Nigeria needed a new kind of builder, someone fluent in both the code and the ledger. Seven months and dozens of policy shocks later, that thesis has been tested by an unusually eventful stretch of the country's economic life.
This isn't a victory lap. It's an honest audit — the same rigor we've applied to every bank, every calculator, and every policy on this site, turned on our own year of predictions.
The Calls That Landed
Bank Recapitalization → Mergers, Not Closures
"The Great Filter" called public offers, forced mergers, and dignified downgrades in January. All three played out almost exactly on schedule by March 31.
The Credit Economy Transition
"The Invisible Handcuffs" predicted cashless policy and recapitalization were two halves of one deliberate shift toward credit-driven consumption. This year's expanded retail lending confirms it.
The Regulatory Squeeze Spread Beyond Banking
"The Liquidity Vacuum" flagged NAICOM and SEC as the next fronts. Insurance recapitalization arrived on schedule in July, running the same playbook as banking.
The Thread That Held Everything Together
Look back across every piece published since January — banking, tax reform, remittances, startup runway, generator costs — and one throughline holds: the gap between the nominal number and the real one is where most financial decisions actually go wrong. Nominal GDP versus real GDP. A nominal raise versus a real pay cut. A stable headline exchange rate versus a real effective one quietly drifting. A generator's fuel bill versus its true cost per kilowatt-hour.
Nigeria has demonstrated this three separate times in just over a decade, and each one is worth memorising:
GDP Rebasing
The economy "doubled" overnight and Nigeria overtook South Africa. Output produced that day: unchanged.
Unemployment Methodology
The rate fell from above 33% to low single digits. Jobs created that day: none.
CPI Rebasing
Headline inflation dropped roughly ten points in a month. Prices that actually fell: none.
Every one of those revisions was statistically legitimate. Every one was also reported in a way that let readers believe something had improved when only the measuring instrument had changed.
"The 'Computational Accountant' this journal called for in January isn't a job title. It's a habit: before you react to any number, ask whether the number moved — or the ruler did."
Where the Next Six Months Are Headed
The recapitalized banking and insurance sectors now have to prove the new capital does more than sit on a balance sheet as a compliance trophy. The tax reforms have to show up as genuinely higher disposable income once inflation is netted out. And the credit economy that's now visibly here has to be met by household discipline, or it becomes the trap this journal warned about back in April, not the tool it can be.
None of that is a prediction of doom or triumph. It's just the next set of numbers to check, the same way we've checked every number since January.
Your Own Mid-Year Audit
Before you close this tab, run the one check that ties the entire year together for your own household: is your bank actually safe under the new capital rules that dominated the first quarter of this story?
Where This Journal Was Wrong, or Too Confident
A scorecard that only lists correct calls isn't a scorecard. Three places where the writing here deserves qualification:
We under-weighted execution risk. The analysis repeatedly treated announced policy as though implementation would follow. Nigeria's own recent history argues otherwise — the 2022 note redesign was a coherent policy destroyed entirely by distribution failure, and NAICOM's 2019 recapitalization was correct in substance and defeated in court. A policy is not an outcome. Several pieces here blurred that line.
We wrote too much for people who already have surplus. Articles on rebalancing portfolios, auditing subscriptions and calculating emergency funds assume money left over at month end. For a very large share of Nigerians, that assumption doesn't hold, and no amount of optimisation advice reaches someone whose income is fully consumed by food and transport. The honest limit of personal finance writing is that it cannot solve an income problem.
We treated "the Nigerian economy" as one thing. A Lagos salary earner with an RSA, a bank account and a Band A connection lives in a different economy from a trader in a smaller city operating almost entirely in cash. Much of the analysis here implicitly addressed the first and generalised to both.
"The habit this journal recommends — checking whether the number moved or the ruler did — applies to its own output too. Otherwise it's just another confident voice."
The Six Months Ahead: What to Actually Watch
Forget forecasts. These are observable indicators that will settle the open questions, and you can track every one of them yourself.
The Dashboard For the Rest of 2026
- Bank results Watch loan-to-deposit ratios. If new capital sits in government securities rather than private-sector credit, recapitalization produced a compliance trophy rather than a financing engine.
- The FX premium The gap between official and parallel rates is the single clearest signal on the currency. Narrow means the rate is clearing; widening means the old pattern is returning.
- Inflation prints Watch the food component specifically, not the headline — it drives the inflation most households actually experience.
- Insurance consolidation Whether NIIRA 2025 survives implementation where the 2019 attempt did not. The test is execution, not the statute.
- Tax receipts Whether the new regime broadens the base as intended, or simply reduces collection from those already compliant.
- Cash in circulation Still rising, or finally flattening? It tells you whether trust in digital rails is genuinely deepening.
If You Only Take Five Things From This Year
The Five Habits
- ☐ Before reacting to any economic number, ask whether the number moved or the ruler did
- ☐ Check your real income change annually — nominal raises hide real pay cuts
- ☐ Build the emergency fund before the investment portfolio; liquidity beats yield at the bottom
- ☐ Match the currency of your assets to the currency of your future obligations
- ☐ Treat every headline rate as marginal, not effective — and do the arithmetic yourself
Tap an item to cross it off.
Questions People Actually Ask
What was the single most important Nigerian economic story of this period? +
Is Nigeria's economy improving? +
What should I do differently in the second half of the year? +
Why does this journal keep returning to nominal versus real? +
Seven months ago, this journal argued the fix for Nigeria's code-and-ledger divide wasn't more meetings — it was a new kind of builder who could hold both languages at once. Halfway through 2026, that builder has had a busy year. There's a lot more ledger left to write.
Let's get back to work.
This article is a fundamental analysis based on publicly available financial data. It is intended for educational purposes only and should not be taken as a recommendation to buy or sell any specific security.
Market data is subject to change. The author (Odiete) may hold positions in some of the assets mentioned. Please consult a licensed financial advisor before deploying capital.
Odiete Oghenesuvwetoba Efemena
Technology Risk & IT Audit
Computer Science graduate and ICAN Professional-level candidate working toward technology risk and IT audit. I write about Nigerian fintech, financial policy, and the systems and controls underneath them.