Mid-Year Inflation Check: Has Your Salary Kept Up?
We're at the halfway mark of the year. Before you look at any national statistic, run the one number that actually matters to your household: has your income grown faster than the prices you actually pay?
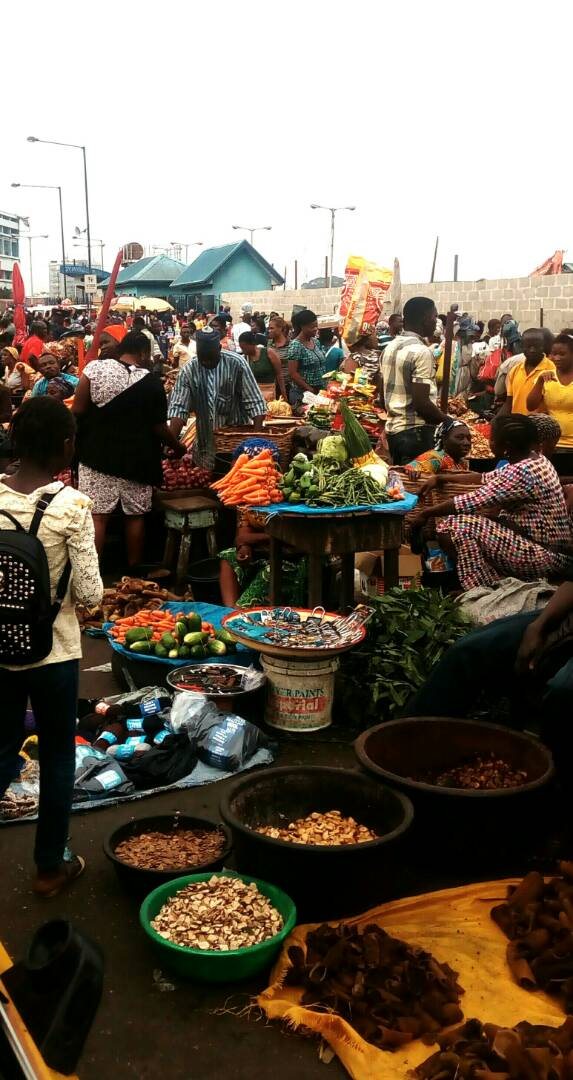
Halfway through the year is a natural checkpoint, and the question worth asking isn't "how is the economy doing" — it's "how am I doing, in real terms, compared to six months ago."
These are not the same question, and conflating them is how people end up feeling confused when a positive GDP headline coexists with their own household budget getting tighter, not looser.
The Only Comparison That Matters
Take your income from the same point last year. Take your income now. Take the inflation rate over that period — the NBS headline figure is a reasonable starting point, though your personal inflation rate may run higher or lower depending on how much of your spend is food and transport-heavy versus not. Compare the growth in your income against the erosion from inflation.
Three Possible Outcomes
- 01.Real gain: your income grew faster than prices. You're genuinely better off, not just nominally.
- 02.Treadmill: your income roughly matched inflation. You feel the same, because you are the same, in real terms.
- 03.Real pay cut: your income grew, but slower than prices. You got a raise and got poorer at the same time — the most common and least discussed outcome.
Careful: The Ruler Itself Changed
Before you compare any headline inflation figure to one from a couple of years ago, know this: the measurement changed.
Nigerian headline inflation peaked at 34.80% in December 2024, the highest in roughly three decades, with food inflation running even hotter. Then, in January 2025, the NBS rebased the Consumer Price Index, updating the base year and modernising the basket of goods it tracks. The reported rate immediately fell to around 24.5%.
// January 2025: inflation "fell" 10 points in one monthDec_2024_headline (old basket) = 34.80%Jan_2025_headline (new basket) = ~24.5%Prices_that_actually_fell = none
Not a single price came down that month. The statisticians simply started measuring a basket that better reflects what Nigerians actually buy in the 2020s. The rebasing was legitimate and overdue — the old basket was anchored to consumption patterns from many years earlier. But it means the pre-2025 and post-2025 series are two different rulers, and any comparison across that boundary is invalid unless it's explicitly rebased.
This is the same trap as the GDP rebasing of 2014 and the unemployment methodology change of 2023. Three times in just over a decade, a headline number moved dramatically for measurement reasons while nothing in anyone's actual life changed. It's the single most important habit this journal can give you: always ask whether the number moved, or the ruler did.
The Minimum Wage Case Study
In July 2024 Nigeria's national minimum wage was raised from ₦30,000 to ₦70,000 a month — a headline increase of over 130%, and by any nominal reading a dramatic win for the lowest-paid workers.
Now apply the test. Over the period bracketing that increase, the Naira had fallen from roughly ₦460 to beyond ₦1,500 against the dollar, petrol subsidy removal had multiplied transport costs, and food inflation was running near 40%. A 130% nominal raise against that backdrop is a far more modest real gain than the headline suggests — and for workers whose spending skews heavily toward food and transport, the personal inflation rate ran well above the national headline.
"A 130% raise sounds unarguable until you measure it against what actually happened to prices. That is not cynicism — it is just arithmetic, and it is the only honest way to read a pay rise in this economy."
Why This Is Worth Doing at the Midpoint, Not Year-End
Finding out in December that you took a real pay cut leaves you nothing to do about it except feel bad. Finding out in June leaves you six months to actually negotiate a raise, pick up additional income, or — at minimum — adjust your spending and saving plan around the reality rather than the illusion of the nominal number on your payslip.
"A raise that doesn't beat inflation isn't a reward. It's a pay cut with better PR."
Run the Numbers
This takes thirty seconds and tells you more about your actual financial trajectory than any national economic report will.
Whatever the result, it's actionable information rather than a vague feeling of being behind. If it's a real pay cut, that's a conversation to have with an employer or a client — with a specific number attached, not just a complaint about the cost of living.
Your Personal Inflation Rate Is Not the National One
The headline CPI is a weighted average across a basket meant to represent a typical household. You are not a typical household, and the gap between your inflation rate and the published one can be very large.
The mechanism is simple: the national basket assigns weights to categories, and your actual spending assigns different ones. Two facts about Nigeria make this gap unusually wide.
Food carries the heaviest weight in the Nigerian basket, and food inflation has consistently outrun headline inflation — running near 40% at the peak, well above the headline rate. So a lower-income household, which spends a much larger share of income on food, experiences an inflation rate materially above the published figure. A higher-income household, where food is a smaller proportion, experiences one below it.
Inflation is therefore regressive in a way the single headline number conceals entirely. The people with the least capacity to absorb price rises are the ones facing the highest effective rate.
"There is no such thing as the inflation rate. There is a national average, and there is what happened to the specific things you buy — and for most Nigerians those two numbers have not been close."
The same logic applies to transport if you commute long distances, to school fees if you have children in private education, and to anything imported if you buy dollar-priced goods. Build a rough weighting of your own spending and you'll get far closer to your real rate than any headline provides.
Using the Number in a Salary Conversation
Knowing you've taken a real pay cut is only useful if it changes something. The conversation goes better when it's framed as arithmetic rather than grievance.
Bring a specific figure: the inflation rate over the period, the raise you received, and the resulting real change. "Prices rose X%, my salary rose Y%, so my real compensation fell Z%" is a factual statement about the world. "Everything is expensive" is a feeling, and feelings are easy to acknowledge and not act on.
Pair it with your contribution over the same period — what you delivered, what you took on, what you'd be paid elsewhere. The inflation figure establishes that maintaining your position requires a certain number; your performance is the argument for exceeding it. And know that the strongest position in any such conversation comes from having options, which is a reason to keep a live sense of your market rate even when you're not looking.
If the answer is no, that answer is also information. An employer that cannot or will not keep pace with inflation is quietly reducing your compensation every year, and it's better to know that in June than to discover it after three more years of erosion.
What Actually Protects You
Negotiating is one lever. It isn't the only one, and for many people it isn't the strongest.
- Income that reprices. Salaried income adjusts once a year at an employer's discretion. Freelance rates, business pricing and rental income can be adjusted as costs move. Any income stream you control the pricing of is structurally more inflation-resistant.
- Assets that grow faster than prices. Cash loses in real terms by construction. Equities and real assets have historically offered better inflation protection over long periods — with volatility that makes them wrong for short horizons.
- Fixed-rate debt. Genuinely counter-intuitive: inflation erodes the real value of money you owe at a fixed rate. If you hold a fixed-rate loan, high inflation is quietly working in your favour on that specific liability.
- Skills that reprice fastest. The most reliable inflation hedge most people have is being worth more next year than this year, in a market that pays for it.
Your Mid-Year Income Audit
- ☐ Calculate your real income change for the last 12 months
- ☐ Estimate your personal inflation rate by weighting food, transport and rent to your actual spending
- ☐ Check whether comparisons you're making cross the January 2025 CPI rebasing boundary
- ☐ Research your current market rate, even if you aren't job hunting
- ☐ Prepare the raise conversation as arithmetic: inflation, raise received, real change
- ☐ Identify at least one income stream whose price you control
- ☐ Review whether your savings are sitting in an account losing to inflation by default
Tap an item to cross it off.
Questions People Actually Ask
Inflation is falling. Does that mean prices are coming down? +
Was the CPI rebasing an attempt to hide the real rate? +
Why does my personal experience feel worse than the published rate? +
Should I ask for a raise every year on inflation grounds? +
This article is a fundamental analysis based on publicly available financial data. It is intended for educational purposes only and should not be taken as a recommendation to buy or sell any specific security.
Market data is subject to change. The author (Odiete) may hold positions in some of the assets mentioned. Please consult a licensed financial advisor before deploying capital.
Odiete Oghenesuvwetoba Efemena
Technology Risk & IT Audit
Computer Science graduate and ICAN Professional-level candidate working toward technology risk and IT audit. I write about Nigerian fintech, financial policy, and the systems and controls underneath them.