One Year Since the Cashless Push: Did It Work?
A year after the aggressive cashless policy push we flagged back in January as connected to the credit-economy transition, here is an honest scorecard: what actually changed, what didn't, and what just moved somewhere else.
Back in January, we argued that the cashless policy push wasn't an isolated headline — it was one half of a deliberate transition toward a credit-based economy, paired with bank recapitalization on the other half. A year later, it's worth an honest scorecard rather than another round of talking points.
First, Remember How Badly It Started
Any honest assessment has to begin with the 2023 cash crunch, because it is the most consequential monetary policy failure in recent Nigerian memory.
In October 2022 the CBN announced a redesign of the ₦200, ₦500 and ₦1,000 notes, paired with severe withdrawal limits — ₦100,000 per week for individuals, ₦500,000 for corporates. Old notes were withdrawn from circulation faster than new ones could be printed and distributed. The result, from December 2022 through February 2023, was a genuine cash famine in a country where most daily commerce still runs on cash: multi-day ATM queues, POS agents charging punitive premiums to dispense notes, and protests in several states. The Supreme Court intervened in March 2023 to keep the old notes legal tender.
It also collided with a general election. Whatever the policy's merits, the execution imposed real hardship on the Nigerians least able to absorb it — traders, daily-wage earners, the unbanked.
What Genuinely Changed
-
01.
Digital payment volume genuinely exploded. NIBSS instant-payment data shows transaction volumes and values rising to levels that would have been unimaginable a few years earlier, with annual value measured in the hundreds of trillions of Naira. Instant bank transfer is now the default settlement method for a huge share of Nigerian commerce.
-
02.
Agency banking became real infrastructure. The POS agent network scaled into the millions of terminals nationwide. Moniepoint, OPay and PalmPay built genuine distribution into places no bank branch reaches — arguably the single most important financial-inclusion development of the decade.
-
03.
Retail credit expanded. The credit-economy transition we predicted is visibly underway, with far more consumer and SME lending products in market than three years ago.
What Didn't Change: Cash Came Back
Here is the finding that should end any triumphalist reading of this policy. After the crunch eased, currency in circulation didn't stay suppressed — it rebounded to record highs, with the overwhelming majority of it held outside the banking system.
Nigerians did not abandon cash. They were briefly deprived of it, and when it returned, many rationally chose to hold more of it than before, precisely because the episode proved that access to your own money could be interrupted by policy.
"The cashless policy succeeded at building digital rails and failed at killing cash. It may even have strengthened the case for holding cash, by demonstrating what happens when the alternative is switched off."
There's a second, less-discussed cost: fraud scaled with the rails. NIBSS reporting has tracked rising fraud volumes alongside rising transaction volumes — a predictable consequence of moving tens of millions of people onto digital payments quickly, and one the eNaira's near-total failure to gain adoption did nothing to offset.
The Honest Scorecard
- ✓Digital rail adoption: succeeded, and beyond expectations
- ✓Agency banking / financial inclusion: succeeded
- ✓Retail credit expansion: on schedule, visibly underway
- ✗Reducing cash in circulation: failed — cash rebounded to record highs
- ✗eNaira adoption: failed almost entirely
- △Execution: caused avoidable, widespread hardship in 2023
"A cashless economy was never really the goal. A credit economy was. Cashless was just the plumbing that made the credit economy possible to build."
The Warning From January Still Stands
We flagged in "The Invisible Handcuffs" that easier credit access is a double-edged tool — it raises living standards today while quietly shifting people from working for their future to working to service their past. A year of expanded credit access makes that warning more relevant, not less. More Nigerians now have access to financing than a year ago; not all of that financing is being priced or used wisely.
Check Where You Actually Stand
If any of that expanded credit access has become idle cash sitting in a low-yield account instead of a deliberate decision, that's worth a look too.
Why Cash Persists — and Why That's Rational
It's tempting to read continued cash use as backwardness. It isn't. Cash does several things digital payments in Nigeria still do not, and every one of them is a reasonable basis for preferring it.
- Cash works when nothing else does. No network, no power, no bank downtime, no failed transaction. In a country with unreliable electricity and periodic telecom congestion, an offline payment method is not a nostalgic preference — it's a functioning fallback.
- Failed transfers are genuinely painful. Anyone who has watched a debit go through while the recipient sees nothing, then spent days chasing a reversal, understands the appeal of an instrument that settles finally and instantly.
- Privacy. Digital payments create a permanent record. There are entirely legitimate reasons to prefer that some transactions not be logged and analysed.
- No minimum, no fee, no float. For small-value trade — the vast majority of Nigerian transactions by count — cash has no per-transaction cost and no settlement delay.
- The 2023 lesson. Millions of people learned that access to digital money could be curtailed by policy. Holding cash after that isn't irrational; it's a directly learned response.
"The people holding cash aren't resisting modernity. They're hedging against a system that has already failed them once, within living memory."
The Real Winner Nobody Planned For
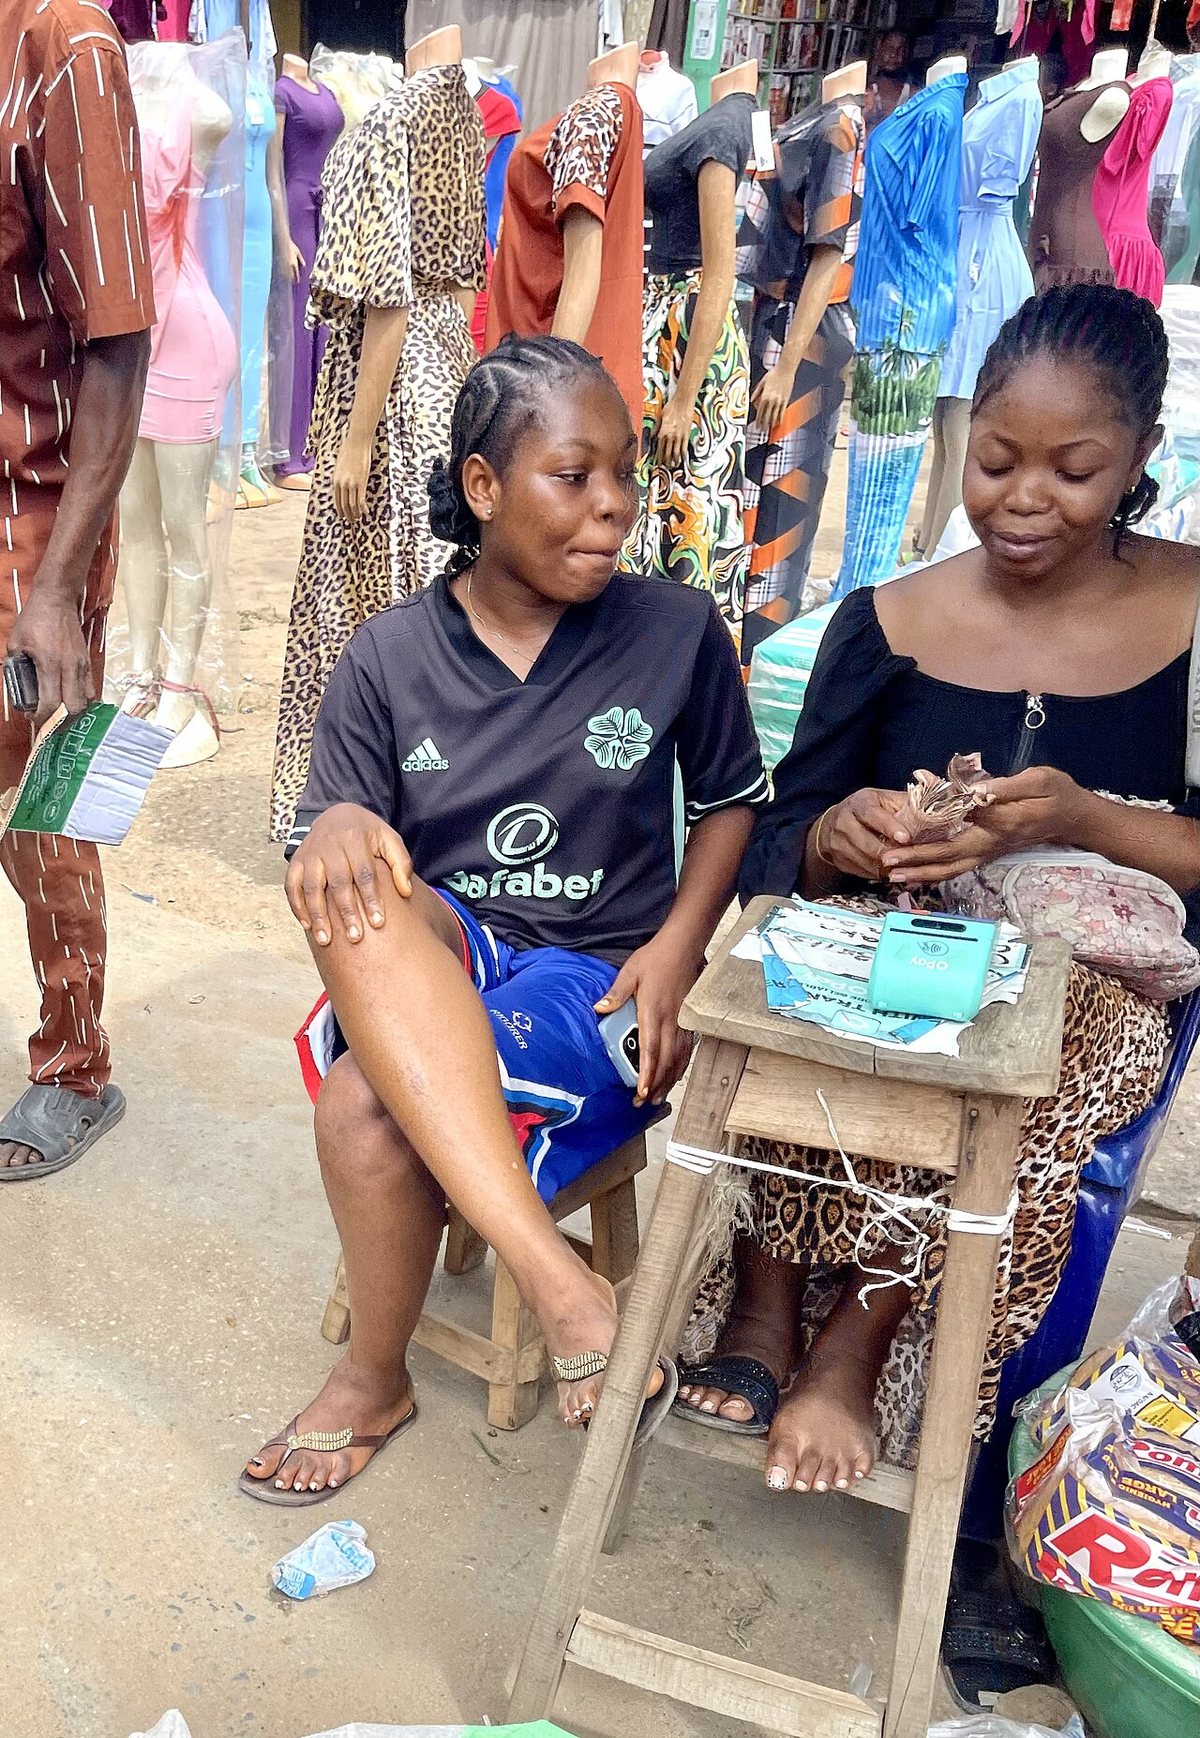
Here is the genuine irony of the entire episode. The cashless policy's most durable achievement was not reducing cash usage. It was building the POS agent network — an industry whose core business is dispensing cash.
The 2023 crunch made agents indispensable. When banks and ATMs couldn't supply notes, agents could, and millions of Nigerians formed a daily habit around them that never went away. Moniepoint, OPay and PalmPay scaled into genuine national infrastructure on the back of it, reaching communities no bank branch has ever served.
So the policy intended to reduce cash handling instead produced the most efficient cash distribution network Nigeria has ever had — while simultaneously, and more importantly, banking millions of previously excluded people. The agent who dispenses your cash also opens accounts, accepts deposits, and processes transfers. Financial inclusion advanced enormously, through a channel the policy did not anticipate and was not designed to create.
Protecting Yourself on the New Rails
Fraud scaled alongside transaction volume, which is the predictable cost of onboarding tens of millions of people quickly. Most Nigerian payment fraud is not technical — it's social engineering, and it's defeated by a small number of fixed rules.
No bank, ever, asks for your PIN, your full card number, your CVV or an OTP. Not by phone, not by SMS, not on WhatsApp, not to "reverse a wrong credit," and not to "upgrade your account." An OTP exists specifically to authorise a transaction you initiated; anyone asking you to read one aloud is asking you to authorise theirs.
The other high-value habits: verify the recipient name before confirming any transfer, keep transaction alerts switched on so an unauthorised debit surfaces within minutes, and treat any message creating urgency — your account will be closed, your BVN will be blocked — as fraudulent by default. Urgency is the signature.
Staying Safe on Digital Rails
- ☐ Never share your PIN, CVV, full card number or any OTP — with anyone, for any reason
- ☐ Confirm the displayed recipient name before completing a transfer
- ☐ Keep SMS and email transaction alerts active on every account
- ☐ Treat urgency in any financial message as a fraud signal
- ☐ Use a licensed POS agent you can identify, not an anonymous roadside terminal
- ☐ Keep a modest cash reserve for outages — the 2023 lesson still applies
- ☐ Report fraud to your bank immediately; speed determines whether a reversal is possible
Tap an item to cross it off.
Questions People Actually Ask
Did the cashless policy fail? +
Why did the eNaira flop? +
Are POS agents safe to use? +
Should I still keep cash at home? +
The cashless push worked, broadly, on its own terms. Whether it worked for you depends entirely on whether the credit and digital access it unlocked got put to deliberate use, or just made spending frictionless in a year when discipline mattered more than convenience.
This article is a fundamental analysis based on publicly available financial data. It is intended for educational purposes only and should not be taken as a recommendation to buy or sell any specific security.
Market data is subject to change. The author (Odiete) may hold positions in some of the assets mentioned. Please consult a licensed financial advisor before deploying capital.
Odiete Oghenesuvwetoba Efemena
Technology Risk & IT Audit
Computer Science graduate and ICAN Professional-level candidate working toward technology risk and IT audit. I write about Nigerian fintech, financial policy, and the systems and controls underneath them.