The Real Effective Exchange Rate: Why "Stable Naira" Headlines Are Misleading
The official rate has barely moved in months, and every headline calls that 'stability.' A quieter number, the Real Effective Exchange Rate, tells a very different story about what's actually happening to the Naira's purchasing power.
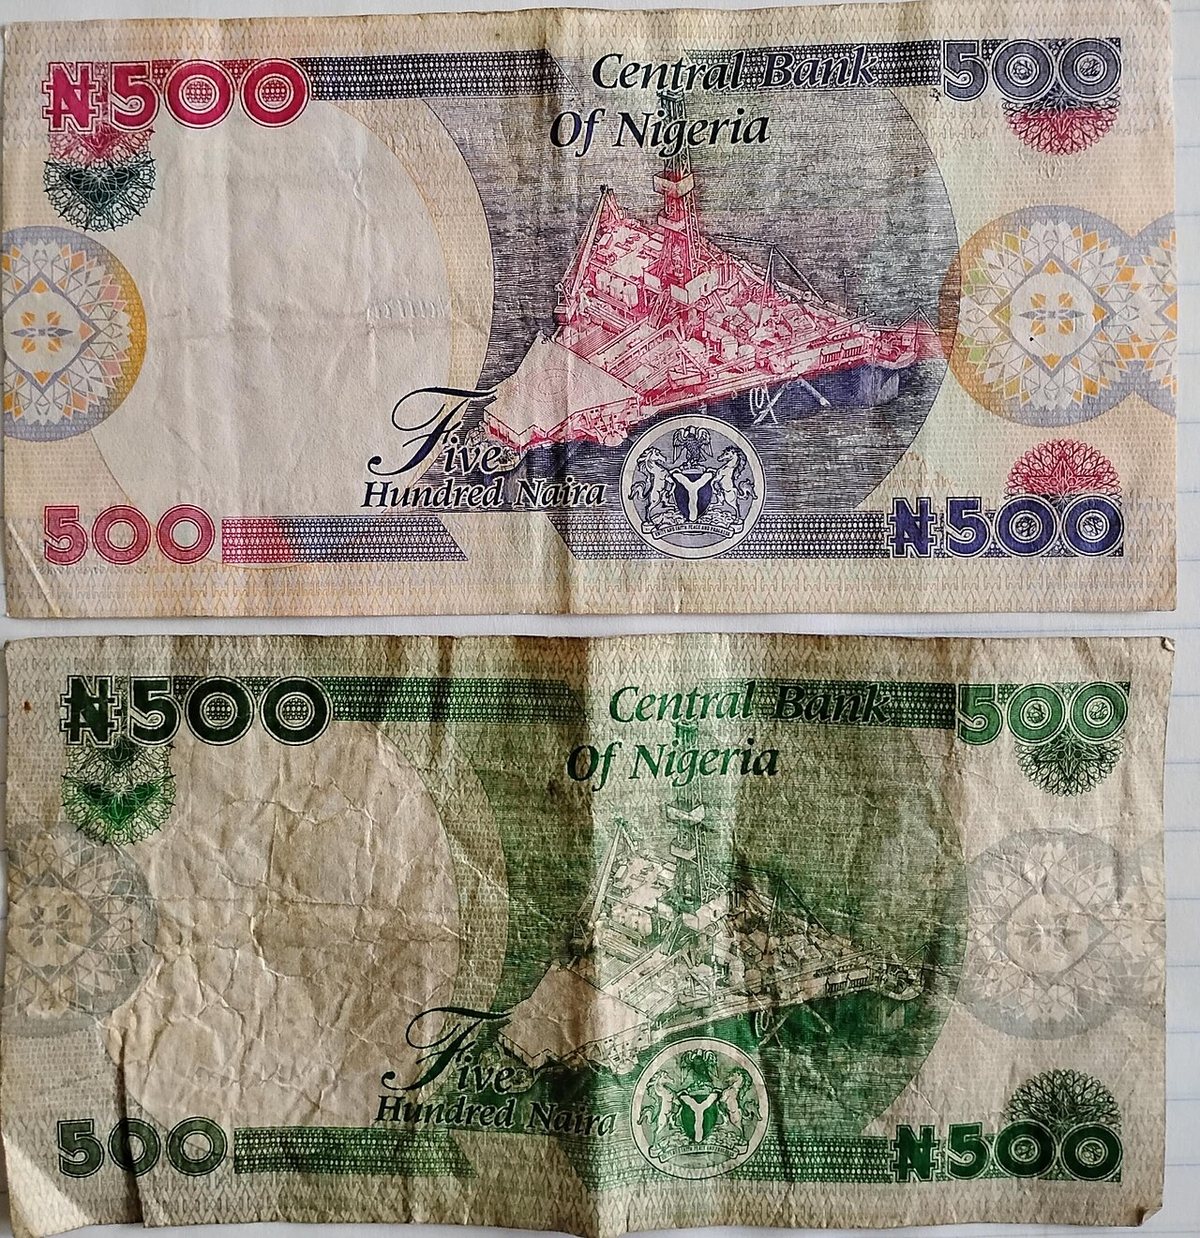
"The Naira has been stable for months" is one of those headlines that's technically true and substantively misleading, depending entirely on which exchange rate you mean.
The official, nominal rate against the Dollar can sit still for an extended period while the Naira is still quietly losing value in a way that matters more to actual purchasing power. The number that captures this is called the Real Effective Exchange Rate, and almost nobody outside a central bank research desk talks about it — which is exactly why it's worth understanding.
Nominal Rate vs. Real Effective Rate
The nominal rate is the number you see quoted everywhere — Naira per Dollar, full stop. The Real Effective Exchange Rate (REER) adjusts that for two things the nominal rate ignores entirely: inflation differentials between Nigeria and its trading partners, and a weighted basket of multiple currencies, not just the Dollar.
// Why "Stable" Can Still Mean "Losing Ground"If Nigeria_Inflation > Trading_Partner_Inflation, REER_Appreciates_in_Real_Terms;// Even while the Naira/Dollar Nominal_Rate holds flat.
A real appreciation sounds like good news, but it's usually the opposite for an economy like Nigeria's — it means Nigerian goods are becoming relatively more expensive versus the rest of the world even without the nominal rate moving, which quietly erodes export competitiveness and widens the gap the parallel market ends up pricing in.
The Gap It Eventually Creates
When the nominal rate is held artificially stable while inflation runs hot domestically, the gap between the "official" world and the "market" world tends to widen rather than disappear. That gap doesn't vanish — it just gets expressed somewhere else: a parallel market premium, or a sudden, sharp devaluation once the pressure becomes unsustainable to hold back.
"A currency held artificially still isn't stable. It's storing energy for a later move — the only question is how it gets released."
Nigeria Has Run This Experiment Twice
You don't need theory to understand what happens when a nominal rate is defended while domestic inflation runs hot. Nigeria has done it twice in a decade, and both times ended the same way.
2015-2016. After the oil price collapsed, the CBN held the official rate near ₦197 to the dollar and rationed access with an administrative list of import categories banned from the official window. The peg held on paper. Underneath, Nigerian inflation was far outpacing that of its trading partners, so in real terms the Naira was becoming steadily more overvalued. The parallel market told the truth the official rate would not — the gap widened until the street rate was multiples of the official one. In June 2016 the CBN capitulated and allowed a devaluation to around ₦280-₦305. The stored energy released all at once.
2020-2023. The same pattern, at greater scale. Multiple official windows quoted rates far below the parallel market for years while inflation climbed. In June 2023 the windows were collapsed and the Naira floated: roughly ₦460 to above ₦750 within days, and past ₦1,500 after further adjustment in early 2024.
// The same script, twiceStep 1: hold the nominal rate steadyStep 2: run inflation well above trading partnersStep 3: watch the parallel-market premium widenStep 4: capitulate — all the adjustment arrives at once
In both episodes, "the Naira has been stable" was a true statement about the nominal rate and a false statement about the currency's actual value. The REER was signalling overvaluation the whole time. Almost nobody was reading it.
Why the Recent Calm Is Different
Here's the fair counterpoint, and it matters: not every period of stability is a peg storing pressure.
The post-2023 stability has a genuinely different character, because the mechanism changed. The CBN introduced an electronic FX matching system for interbank trading in December 2024 and published a formal FX Code, moving price discovery onto transparent, observable infrastructure. The decisive evidence is the parallel market premium: through 2025 the gap between official and street rates narrowed to a fraction of what it had been, at times nearly closing.
That is the test. A rate held stable by administrative fiat shows up as a widening parallel premium. A rate stable because the market clears at that level shows a narrow one. Same nominal stability, opposite meanings — and the premium is the tell.
What This Means for Your Spending
Regardless of what the headline exchange rate says this week, every imported good in your basket is still transmitting real currency pressure through to the price you pay. That mechanism doesn't pause just because the official quote didn't move.
Who Wins and Loses From an Overvalued Currency
Currency policy is often discussed as a technical matter. It isn't. An artificially strong Naira is a transfer of wealth between identifiable groups, and knowing which side you're on explains a great deal about Nigerian economic politics.
Gains from an overvalued Naira
- Importers — foreign goods are artificially cheap
- Anyone paying school fees or medical bills abroad
- Travellers buying foreign currency at the official rate
- Holders of dollar-denominated debt
- Whoever obtains scarce official-rate FX during rationing
Loses from an overvalued Naira
- Exporters — their goods are priced out of world markets
- Local manufacturers competing with cheap imports
- Farmers competing against subsidised imported food
- Anyone earning foreign currency and converting to Naira
- The economy's long-run capacity to produce tradeable goods
That last item is the one that compounds. Sustained overvaluation makes it structurally unprofitable to manufacture domestically and structurally profitable to import — so an economy quietly reorganises itself around trading rather than making. Reversing that takes years, long after the rate itself has been corrected.
The rationing dynamic deserves its own note. When an official rate is held below the market rate, demand exceeds supply and the FX must be allocated administratively rather than by price. Whoever secures dollars at the official rate captures the difference between official and parallel — a substantial, risk-free gain available only to those with access. That gap is not merely an economic distortion; it is a standing invitation to rent-seeking, and it was among the strongest arguments for unification.
"A wide parallel premium is not just bad economics. It is a subsidy paid by the whole country to whoever has access to the official window."
How to Read the Naira Yourself
You don't need REER data to apply the core insight. Three observable indicators tell you most of what matters.
The parallel premium. The single best indicator available to an ordinary person. Compare the official rate to the street rate. A narrow gap means the official rate is roughly where the market clears. A widening gap means pressure is building that will eventually be released.
The inflation differential. If Nigerian inflation runs well above that of its trading partners while the nominal rate holds flat, real overvaluation is accumulating by definition — regardless of how calm the headline looks.
Reserves and the source of stability. A rate held stable because reserves are being spent to defend it is a different thing from one stable because supply and demand balance at that level. The first is finite; the second is durable.
Reading the Naira Without a Bloomberg Terminal
- ☐ Track the gap between official and parallel rates — the single clearest signal
- ☐ Compare Nigerian inflation against major trading partners' inflation
- ☐ Ask whether stability is coming from market clearing or from reserve spending
- ☐ Match your savings currency to the currency of your future obligations
- ☐ Don't treat a stable headline rate as a reason to abandon FX-risk planning
- ☐ If you have foreign-currency goals, build toward them steadily rather than timing a move
Tap an item to cross it off.
Questions People Actually Ask
Is a strong currency good for a country? +
Should I hold dollars given this history? +
Why can't the CBN just fix the rate at a good level? +
Is the recent stability going to last? +
The Takeaway
Don't plan your finances around the headline stability of the nominal rate. Plan around the underlying inflation differential that the REER captures — it's a slower-moving, less dramatic number, but it's the one that actually predicts where the "stable" rate eventually has to go.
This article is a fundamental analysis based on publicly available financial data. It is intended for educational purposes only and should not be taken as a recommendation to buy or sell any specific security.
Market data is subject to change. The author (Odiete) may hold positions in some of the assets mentioned. Please consult a licensed financial advisor before deploying capital.
Odiete Oghenesuvwetoba Efemena
Technology Risk & IT Audit
Computer Science graduate and ICAN Professional-level candidate working toward technology risk and IT audit. I write about Nigerian fintech, financial policy, and the systems and controls underneath them.